
August 2026 has brought a new level of complexity to the New Zealand Mortgage market. Interest rates may be finding some stability, but that does not mean borrowing has become simple. For many Kiwis, the real challenge is no longer just finding a rate. It is finding a lender and lending policy that actually fit their circumstances.
The old approach of walking into your main bank and expecting a straightforward answer is becoming less reliable. Banks are tightening their belts, lending rules are more conservative, and viable borrowers can still find themselves outside a particular bank's box.
That is why mortgage brokers have become essential navigators in the modern New Zealand Mortgage landscape. The verdict is clear: before making decisions about your next loan, talk to your advisor.
Table of Contents
- 📊 A More Complex New Zealand Mortgage Environment
- 🏦 Why Main Banks Are Becoming More Cautious
- 🧭 The Strategic Advantage of a Mortgage Broker
- ✅ Do Not Treat Your Existing Bank as the Only Option
- 📋 The Practical Verdict for Borrowers
- ❓ New Zealand Mortgage FAQs
📊 A More Complex New Zealand Mortgage Environment
The New Zealand Mortgage market is at a pivotal point. Rates have stabilised compared with more volatile periods, yet they remain high enough to put real pressure on affordability, servicing calculations and household budgets.
Stability is welcome, but it should not be confused with ease. When rates stay elevated, the gap between one lending decision and another can be significant. A borrower may be able to meet repayments in practical terms but still fall short under a lender's assessment model, expense assumptions or preferred lending criteria.
That is the central issue. Lending is no longer one-size-fits-all.
Every lender has its own appetite for risk, its own policies and its own way of looking at an application. A decision from one bank is not necessarily a final answer on your borrowing options.
🏦 Why Main Banks Are Becoming More Cautious
Local banks are increasingly risk-averse. Tighter lending rules mean they are applying more scrutiny to applications and making fewer exceptions to standard policy.
For borrowers, this can be frustrating. You may have a solid income, a meaningful deposit, a good repayment history or a workable plan, but a particular bank may still say no because your application does not align with its current criteria.
This is not always a reflection of whether the loan makes sense. It can simply be a reflection of that lender's policy at that moment.
There are several areas where the New Zealand Mortgage process can become more demanding:
- Serviceability assessments: lenders closely test whether repayments remain manageable at their required assessment rates.
- Income treatment: salaries, self-employed income, bonuses and other earnings can be assessed differently from one lender to another.
- Living-expense assumptions: the way a lender interprets household spending can materially affect borrowing capacity.
- Policy fit: a borrower may not suit one bank's rules but may be a strong fit for another lender.
The Reserve Bank of New Zealand's lending restrictions information provides useful context on the wider framework shaping residential mortgage lending. But the practical outcome is straightforward: borrowers need to understand the policy landscape, not just compare a headline interest rate.
🧭 The Strategic Advantage of a Mortgage Broker
A mortgage broker brings two things that a single bank cannot: choice and policy depth.
Rather than assessing your circumstances through one lender's framework, an advisor can consider a broader range of options and identify where your application is most likely to fit. That matters in a market where lender policies can differ just as much as their advertised rates.
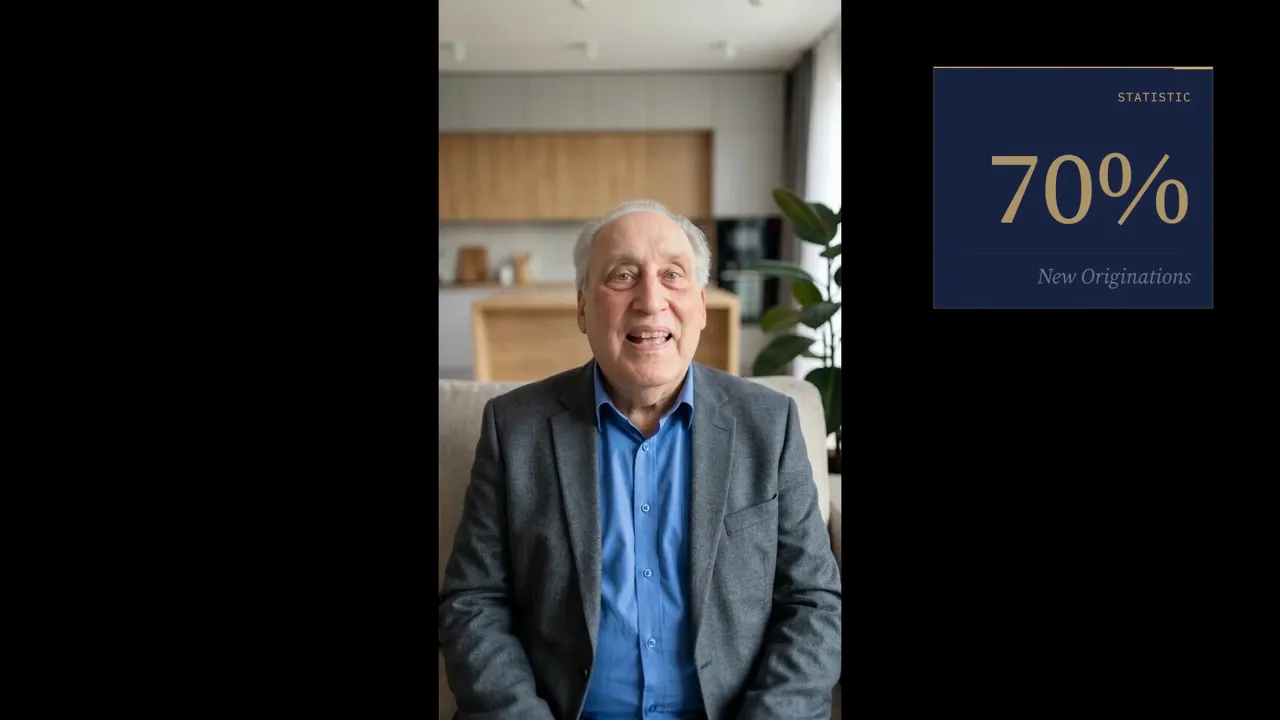
Brokers now handle around 70% of new originations. That shift reflects the value of having an expert navigate lending conditions, compare available pathways and help borrowers avoid being limited to the first answer they receive.
In the current New Zealand Mortgage market, an advisor's value is not simply filling out paperwork. It is understanding lender appetite, interpreting policy and positioning an application appropriately.
A good advisor helps you consider questions such as:
- Which lenders are most suitable for my situation?
- How will different lenders assess my income and expenses?
- What loan structure best supports my current position?
- Are there competitive options I may miss by approaching only my existing bank?
✅ Do Not Treat Your Existing Bank as the Only Option
There is nothing wrong with speaking to your bank. The issue is making it your only call.
Your current bank knows your accounts, but it can only offer its own products and work within its own lending policy. It cannot compare its position against the wider lending market for you.
That is why the first conversation in a New Zealand Mortgage decision should be with your advisor. Start with a full view of the available options, then decide which path makes the most sense for you.
This approach is particularly important when refinancing, buying a first home, restructuring existing debt or dealing with a more nuanced income position. The right loan is not always the one with the most familiar logo. It is the one that provides a competitive, workable fit for your circumstances.
📋 The Practical Verdict for Borrowers
The message is simple. Do not assume a bank's first answer is the only answer available to you.
When the New Zealand Mortgage market is complex, the most practical next step is to:
- Call your advisor. Begin with someone who can assess the wider market rather than one lending policy.
- Review your options. Compare loan structures, lender criteria and competitive credit opportunities.
- Secure your future. Make a lending decision based on a clear understanding of what is available and what suits your position.
Interest-rate stability does not remove the need for strategy. If anything, it makes the quality of the lending decision even more important. A New Zealand Mortgage is not just about getting approved. It is about finding the right competitive credit solution for where you are now and where you want to go next.
❓ New Zealand Mortgage FAQs
Why should I speak with a mortgage advisor before my bank?
An advisor can assess a broader range of lender options and policies. Your bank can assess only its own products and criteria, while an advisor can help determine whether other lenders may be a better fit.
Does stable interest-rate pricing mean it is easier to get a New Zealand Mortgage?
Not necessarily. Rates can be stable while lending assessments remain strict. Serviceability tests, income treatment, expenses and lender policy can all affect the outcome.
Why do different lenders give different mortgage answers?
Each lender has its own risk appetite and lending policy. A borrower who does not meet one bank's criteria may still be suitable for another lender.
What does a mortgage broker add to the process?
A broker provides lender choice, policy knowledge and guidance through the application process. In a complex New Zealand Mortgage market, this can help borrowers identify options that may otherwise be missed.
Comments
Post a Comment